A mattress should ease the strain you feel when you wake up, not create a new strain every month when the payment is due. A clear mattress financing comparison puts the real decision in focus: not just how low the monthly payment looks, but what you will pay in total for better spinal support, cooler sleep, and undisturbed nights.
For many households, financing makes a quality hybrid mattress more reachable without waiting months to save the full amount. That can be a sensible choice when your current bed is contributing to back stiffness, pressure points, overheating, or sleep interrupted by a partner’s movement. The right plan, however, depends on its annual percentage rate, repayment timeline, fees, and whether the monthly payment truly fits your budget.
Mattress Financing Comparison: Start With Total Cost
A $1,200 mattress can look very different depending on how you pay for it. Paying cash means the price is straightforward: $1,200, plus any applicable tax. A genuine 0% APR plan spread over 12 months may also cost $1,200, paid as $100 per month. Interest-bearing financing could cost considerably more, even if the advertised payment is only $50 or $60 each month.
The monthly figure is useful, but it should never be the deciding figure on its own. Longer terms reduce the payment while increasing the time you carry the obligation. When interest applies, they often increase the total cost as well.
Before selecting a financing option, find four numbers: the mattress price, the amount due today, the number of payments, and the total of all payments. If a lender does not make those details easy to understand, pause before proceeding. Sleep should feel like a long-term investment in recovery, not a confusing financial commitment.
How Common Payment Options Compare
Most mattress shoppers will encounter cash or card payments, buy now pay later plans, promotional store financing, and standard installment loans. Each can work well in the right circumstances.
Cash, debit, or a paid-in-full credit card
Paying in full is usually the simplest route. There is no financing application, no repayment schedule to track, and no interest cost. If you use a credit card, this only remains the lowest-cost option if you can pay the statement balance in full before interest begins.
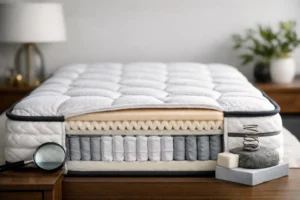
Cash payment also makes it easier to compare mattresses based on construction rather than promotional terms. You can focus on the features that affect nightly comfort: pressure-relieving comfort layers, responsive pocketed coils that support alignment, cooling materials that help manage heat, and motion isolation for couples.
The trade-off is immediate cost. Paying $1,000 or more at once may not be practical, especially when replacing a mattress unexpectedly or furnishing a new home.
Buy now pay later plans
Buy now pay later, often called BNPL, commonly divides a purchase into a small number of fixed payments. Some plans offer four interest-free payments every two weeks, while others offer monthly terms that may include interest depending on the provider and your eligibility.
This approach can be useful for a buyer who has steady income and wants to divide a manageable expense without carrying a large revolving credit card balance. Its shorter repayment window is also a benefit for people who prefer to be finished quickly.
Still, the payment frequency deserves attention. Four payments every two weeks can feel faster than a monthly plan, and missed payments may result in late fees or other consequences. Check whether automatic payments are required, what happens if a payment fails, and whether the provider reports payment activity to credit bureaus.
Promotional 0% APR store financing
A 0% APR promotion can be one of the strongest values in a mattress financing comparison, but only if it is truly zero interest for the full term and you make every required payment on time. When the price and repayment schedule are clear, this option lets you choose a more supportive mattress now while preserving cash flow for other priorities.
Read the promotion language carefully. “0% APR for 12 months” is not always the same as “no interest if paid in full within 12 months.” The second phrase may indicate deferred interest. If the balance is not paid completely by the deadline, interest can sometimes be charged retroactively from the original purchase date. That can turn an appealing promotion into an expensive one.
Set up automatic payments and aim to pay more than the stated minimum when deferred interest is involved. The safest approach is to divide the full purchase price by the number of promotional months, then schedule that amount so the balance reaches zero before the deadline.
Standard installment loans
Some financing providers offer fixed monthly payments over longer periods, with an APR based on creditworthiness. The advantage is predictability: you know the payment date and, in many cases, the total repayment amount before accepting the agreement.
This can be reasonable when a shorter no-interest option would make the monthly payment uncomfortable. But compare the APR with your other options. A mattress built for durable comfort and proper support can be worth the investment, yet high-interest financing may reduce the value of a sale price quickly.
Match the Term to the Mattress, Not the Marketing
A quality mattress is used every night, so it is understandable to prioritize materials and performance over the lowest upfront price. A hybrid design can combine contouring foam or latex with individually pocketed coils to support the spine, reduce pressure around the shoulders and hips, improve airflow, and limit motion transfer. Those benefits matter if you are waking sore, sleeping hot, or losing rest when your partner moves.
Financing should support that decision, not distract from it. Do not stretch into a higher-priced model only because a lender shows a low monthly number. Instead, decide which sleep problems your mattress needs to solve, establish a realistic all-in budget, and then choose the shortest affordable repayment term.
For example, a $1,500 mattress at 0% APR over 12 months costs $125 per month. Over 24 months, it costs $62.50 per month if the offer remains genuinely interest-free. The 24-month plan can be perfectly reasonable if it offers the same total price and leaves room in your budget. But if the longer term carries interest, the lower payment may hide a higher final cost.
Costs and Conditions That Deserve a Closer Look
The headline APR is not the only detail that matters. Financing agreements can include terms that change the value of the offer.
Look for an origination fee, monthly account fee, late fee, returned-payment fee, prepayment penalty, and the consequences of a missed payment. Also confirm whether a down payment is required and whether tax, delivery, accessories, or an optional protection plan are financed separately. A pillow or topper may improve your complete sleep setup, but adding extras should be a deliberate choice rather than a way to fill out a financing cart.
It is also wise to check the return policy before financing a mattress. A comfortable trial period, transparent return process, and meaningful warranty help reduce the risk of committing to a product you have not slept on for long. Financing can be canceled or adjusted after a return in many situations, but the process and timing vary by retailer and lender. Keep your receipts, payment confirmations, and return documentation until the account shows a zero balance.
When Financing Makes Sense and When It Does Not
Financing makes sense when it allows you to replace a worn-out mattress with a better sleep solution while keeping payments predictable and interest costs low or zero. It can be especially practical for a couple replacing an old bed that transfers every movement, or for someone whose morning aches signal that their current surface is no longer providing support.
It may not be the right choice if the payment would force you to carry revolving debt elsewhere, if the promotional terms are difficult to explain, or if you are relying on uncertain future income to make the installments. In that case, consider a lower price point, wait for a planned promotion, or save toward the purchase while continuing to evaluate the features you need most.
A mattress is not merely a large item in a checkout cart. It is the surface beneath your spine for hours each night, the place where joints recover, and the foundation for a more focused day. Choose the payment plan with the same care you give the mattress itself: clear terms, manageable payments, and no surprises standing between you and truly restorative rest.